Recently, amid a confluence of factors including shifts in the overseas macroeconomic policy cycle, repeated fluctuations in rate cut expectations, and personal events involving the company's management, the stock price of a leading overseas AI computing power enterprise has retraced over 30% in a single month.
At the current juncture, the market is beginning to discuss whether this presents an observation window with a relatively favorable risk-reward ratio. Based on recent industry fundamentals, we analyze from three dimensions whether current market concerns have peaked.
I. Policy Disturbance: Data Center Construction Is Merely Delayed, Not Cancelled
The market previously feared that shifts in policy direction in certain key overseas electoral districts could severely suppress AI infrastructure construction, thereby affecting the performance of the entire supply chain.
However, industry chain research suggests this concern may be an overreaction:
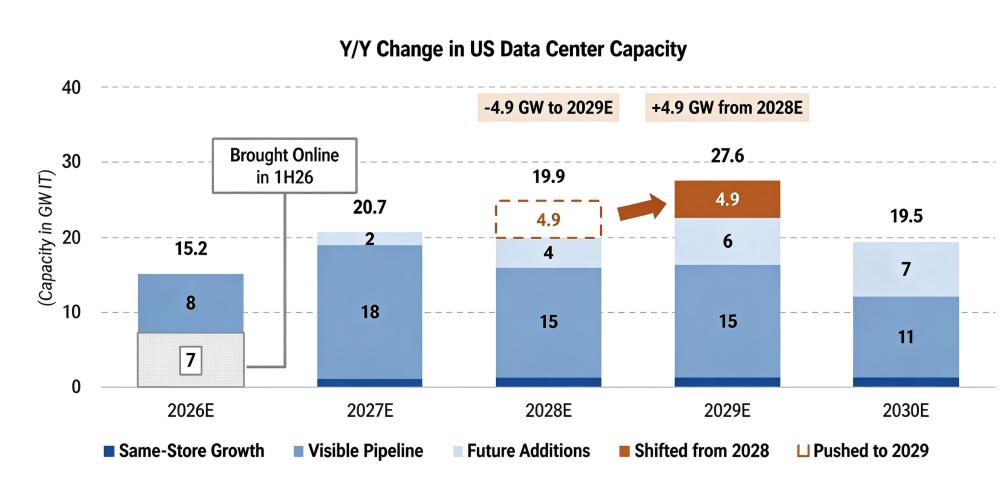
First, the data center construction plan for 2027 remains unaffected, as most projects for 2026 have already completed the approval process.
Second, even if the approval pace in certain regions slows down, it largely just postpones part of the 2028 demand to 2029, without changing the overall upward trend in demand.
Third, influenced by the domestic policy environment, high financing costs, and power supply shortages, U.S. domestic data center construction is showing a trend of shifting to regions such as Europe and Southeast Asia.
II. Macro Interest Rates: Rate Hikes Are More of a Preventive Response, Not the Start of a Long-Term Cycle
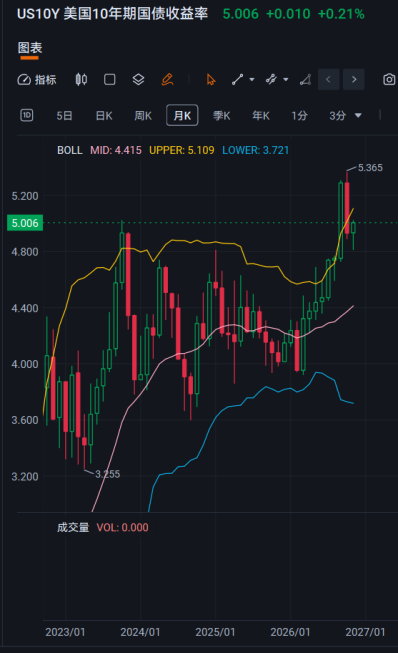
Recently, even the most hawkish Federal Reserve officials have stated that a rate hike of 150-200 basis points is unlikely. Coupled with the decline in oil prices, the U.S. 10-year Treasury yield has fallen from its high of 5.4% to 5% or below.
From a macro liquidity perspective, rate hikes are unlikely to evolve into a major cycle, and even less likely to become the core factor piercing the AI industry trend, as the underlying computing power demand driven by the explosion of AI applications remains strong.
III. Corporate Governance: The Long-Tail Impact of Management's Personal Events Is Limited
This computing power giant possesses mature core technologies and a modern corporate management system. Its management structure has long moved beyond a single top-down architecture. Even though management's personal influence is strong, the market has likely already priced in the worst-case scenario of this turmoil.
If management continues to serve, the company is expected to emerge from the turmoil at the public opinion level in the near future.
IV. Earnings Certainty and Valuation Attractiveness
After the sharp decline, the leader's forward P/E has fallen to 12x (based on 2027 expected earnings), matching its industry net profit CAGR of over 50%. The PEG ratio is far below 1, indicating a relatively high margin of safety from a valuation perspective.
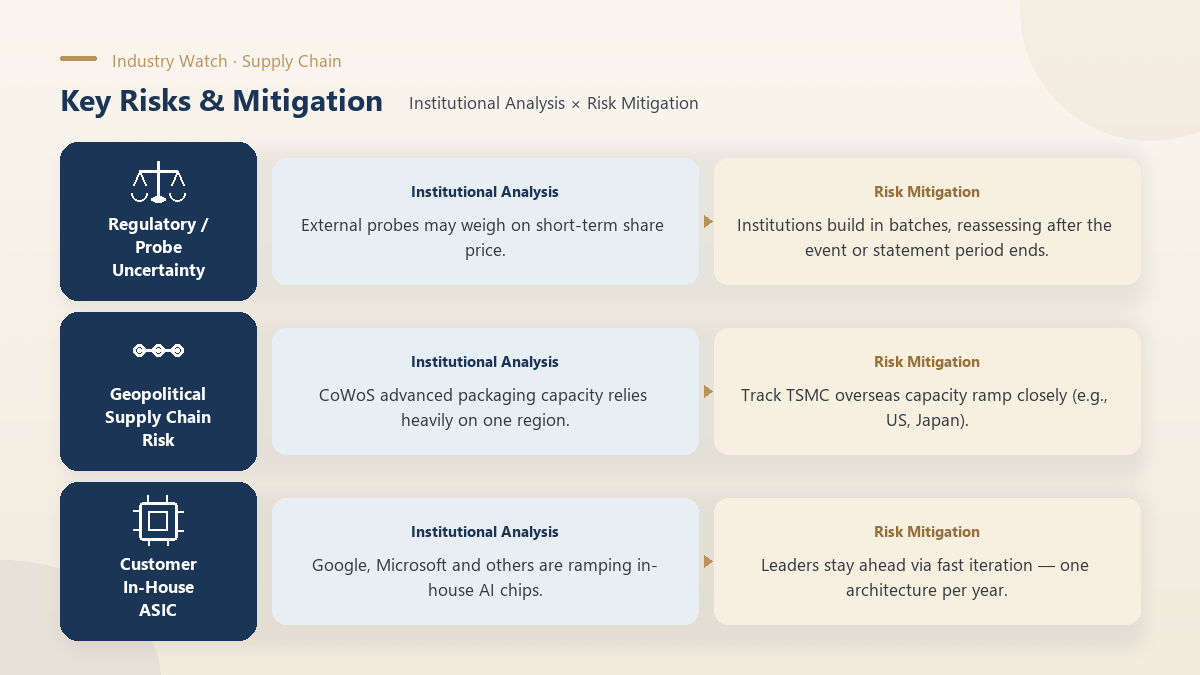
V. Mainstream Industry Observation Framework: Core Risks and Response Strategies
Within a compliant context, we do not provide any specific operational advice. However, when constructing global asset allocation strategies, investors typically refer to the following institutional perspectives on risk response frameworks:
Conclusion
From a fundamental perspective, the underlying demand in the AI computing power industry chain remains strong. Short-term macroeconomic disturbances and sentiment-driven sell-offs often provide long-term investors with a window to re-examine the valuation and future growth of core assets. In market volatility, maintaining rational judgment and scientific position management is often more important than mere prediction.
DISCLAIMER
The information contained in this document has been prepared based on publicly available information. des Voeux Partners Limited ("DVP") in preparing this document, and des Voeux Family Office Limited ("DVFO") in reproducing this document, have taken reasonable care to ensure that the information contained herein is accurate and objective. However, neither DVP nor DVFO makes any representation or warranty as to the accuracy or completeness of the information contained in this document (including any valuation mentioned herein), nor has any independent verification of such information been conducted. DVP makes no representation or warranty as to the adequacy, completeness, or suitability of this document for any particular purpose.This document merely provides a macroeconomic overview of recent economic and market developments and is intended solely for marketing and reference purposes. This document is not an investment research report, nor should it be regarded as investment research. The preparation of this document has not complied with legal requirements intended to promote the independence of investment research, nor is it subject to any prohibition on dealing ahead of the dissemination of investment research. Unless otherwise specified, the source of information contained in this document is DVP. The opinions expressed herein represent the views of the author as of the date of writing and are subject to change at any time without prior notice. Any forecasts, estimates, or targets mentioned in this document are for reference only and are not guaranteed to be achieved. DVP and the author assume no liability for any failure to achieve such forecasts, estimates, or targets. In the event of any discrepancy or inconsistency between the Chinese and English versions of this document, the English version shall prevail.No person should rely solely on the contents of this document to make any investment or other decisions. All relevant decisions should be based on your independent judgment and after consulting appropriate professional advisers.This document does not constitute an offer or invitation to buy or sell any securities, financial instruments, or other investment products by DVP or its affiliates, nor does it constitute any investment, accounting, legal, or tax advice. The contents of this document shall not be regarded as investment advice, an offer, or a solicitation provided to any individual.Investing in any products mentioned in this document involves varying degrees of risk, including credit risk, market risk, liquidity risk, legal risk, cross-jurisdictional risk, foreign exchange risk, and other risks associated with electronic trading and leveraged product trading. Investment inherently carries risk, and you may not recover your full principal amount invested. Prices of investment products may fluctuate significantly, going up or down, and may even become valueless. Buying and selling investment products carries the risk of incurring losses rather than making profits.Nothing in this document constitutes personalized accounting, legal, regulatory, tax, financial, or other professional advice tailored to the personal circumstances of the reader. Before investing in any product, you should consult your own financial, legal, tax, or other professional advisers to fully understand the relevant risks and assess whether you are suited to bear such risks.All descriptions of any investment products herein are subject to the terms and conditions of the respective investment product and, where applicable, the prospectus or other relevant offering documents accompanying such investment product.To the maximum extent permitted by applicable laws and regulations, DVP, DVFO, and their affiliates shall not be liable for any loss or damage of any kind arising from any action taken or not taken by any person in reliance upon any information, opinion, forecast, or valuation contained in this document, regardless of how such loss or damage arises.This document and its contents are intended solely for professional investors as defined in the Securities and Futures (Professional Investor) Rules (Cap. 571D) of Hong Kong. This document and its contents have not been reviewed by the Securities and Futures Commission of Hong Kong (SFC).